INSURANCE FOR CONTRACTORS. THE STUFF YOU HATE TO PAY FOR.

Workers comp, general liability, business auto, and bonds, from a guy who works with contractors. I get my clients great pricing, I send out COIs immediately, and I get very involved with workers comp audits so you don't get hit with wrong payrolls or cost of subs.

LISTEN UP GUYS...
INSURANCE MADE CLEAR
PREMIUM AUDIT
DUE NOW
Workers' comp audit
General liability audit
Additional premium due

Was it in your bid?

  • CONTRACTOR INSURANCE
  • GREAT PRICING
  • COIs OUT IMMEDIATELY
  • I WORK YOUR WORKERS COMP AUDIT
  • THE STUFF YOU HATE TO PAY FOR
  • NOBODY EVER TELLS CONTRACTORS THIS STUFF
  • I'M NOT A ROCKET SCIENTIST EITHER
  • TEXT 201-254-4117

WHAT I HANDLE

WORKERS COMP. GENERAL LIABILITY. BUSINESS AUTO. BONDS.

Four policies, one guy who reads them. Pick the one that's bugging you.

Andy with his hand on a contractor's shoulder

Workers Compensation

Rated on your payroll by class code, then audited after the year ends. Did your payroll increase? Did your class codes change? Did you start using more subcontractors? Did your experience mod go up? Did anybody sit down and review all of this? If not, you could get absolutely crushed at audit time. And the auditor isn't showing up with balloons and a fruit basket.

Review mine
Andy holding an umbrella over a small jobsite

General Liability

Contractors think "I'm good, I have a million dollar policy." Nope. Not even close. A million dollar policy sounds wonderful until you find out what it doesn't cover. What endorsements are on the policy? What exclusions are buried inside? Are you covered for residential work? Roofing? Excavation? NY Labor Law exposures (the dreaded Action Over!)? Is your additional insured wording correct? Are your subcontractor requirements correct? Most contractors have no clue. And sometimes their agent doesn't either.

Review mine
Andy leaning on a white work van with keys

Business Auto

Pickup trucks. Work vans. Dump trucks. Dump trailers. Personal vehicles being used for business. And half the time the coverage is completely wrong: wrong drivers, wrong vehicles, wrong usage, missing vehicles, not enough coverage. One bad accident, and what you thought was a little insurance problem becomes a very big contractor problem.

Review mine
Andy holding a sealed bond certificate

Bonds

License Bonds, Bid Bonds, Performance Bonds. When a GC or a municipality asks for one, you need it fast and priced right. Send me the requirements and I'll handle it.

Review mine

WHY ANDY

3 BIGGEST THINGS MY CLIENTS TELL ME...

Andy holding four insurance quotes fanned out like playing cards01

I get them great pricing.

Andy handing over a certificate of insurance while holding a stopwatch02

I send out COIs immediately.

Andy working through a workers comp audit at his desk03

I get very involved with workers comp audits so you don't get hit with wrong payrolls or cost of subs.

Need a certificate right now? Text me the GC's requirements.

Text Andy

THE RENEWAL TRAP

SIGN. PAY. HOPE NOTHING GOES WRONG.

Most contractors renew their insurance the same exact way every year. Same workers comp policy. Same general liability policy. Same business auto policy. Sign. Pay. Hope nothing goes wrong. And then... BAM! A claim happens. And suddenly everybody starts pointing fingers.

Oops... your policy excluded that.

Oops... your payroll was wrong.

Oops... your vehicles weren't listed correctly.

Oops... you don't have the right additional insured wording.

Oops... your subcontractor coverage has problems.

SUCKS!SUCKS!SUCKS!

OOPS??? THIS IS MY BUSINESS WE'RE TALKING ABOUT!!!

NOBODY EVER TELLS CONTRACTORS THIS STUFF!

FREE POLICY REVIEW

WHY THE HECK SHOULD ANDY THE INSURANCE GUY REVIEW MY INSURANCE POLICIES?

Because there's a very good chance you're paying too much, you're missing important coverage, or you're setting yourself up for a disaster and don't even know it.

A REAL REVIEW.

Not fast. Not lazy. Not "here's your renewal invoice, please sign here." Andy the Insurance Guy looks at insurance the way contractors need it reviewed. I help contractors understand the problems they deal with:

  • Audits
  • Certificates of Insurance
  • Subcontractors
  • Additional Insured Requirements
  • Claims
  • Payroll Changes
  • Vehicles
  • Contract Requirements

And all the other fun stuff that makes contractors say "why the heck is insurance so complicated?"

WHAT'S THE GOAL?

  • Protect your business.
  • Lower your risk.
  • Hopefully save you money.
  • Catch problems before they become very expensive problems.

Because fixing a bad insurance policy after the claim happens? Too late!

WANT ANDY THE INSURANCE GUY TO TAKE A LOOK?

I'll review your workers compensation, general liability, and business auto. And hopefully I find a better solution and save you some money.

And maybe Andy the Insurance Guy saves the day! Hey... a guy can dream.

THERE'S A VERY GOOD CHANCE NOBODY HAS EVER REVIEWED YOUR INSURANCE POLICIES THE RIGHT WAY. LET'S FIND OUT BEFORE YOUR NEXT CLAIM OR AUDIT DOES IT FOR YOU.

BID MATH

WAIT... I LOST MONEY ON THAT JOB?!

You finished the job. You got paid. You thought you made good money. Then your workers' comp audit came, your general liability audit came, and you owed a whole lot more money than you expected.

That bill is the insurance cost of work you already did, charged after the fact. Your policy was priced on an estimate of your payroll. After the policy year ends, the auditor counts the real payroll, puts each job in the right class code, adds any sub you couldn't produce a certificate for, and bills the difference. If your bids never included that cost, the audit takes it out of your profit.

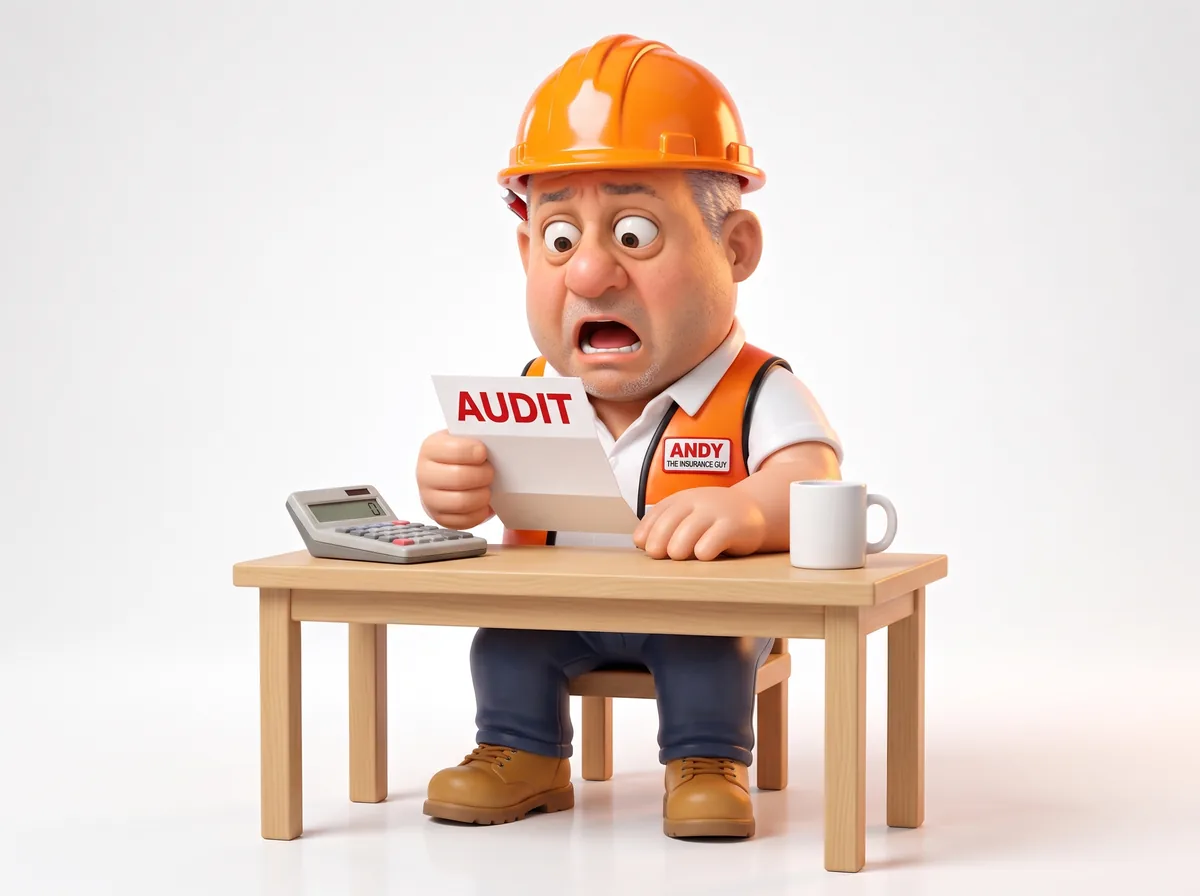
Andy reading an audit letter in shock
Illustration: two audit bills shrink the profit you thought you made.

Hate when that happens...

PRICE THE JOB THE RIGHT WAY. IT'S NOT HARD.

We all get excited about the big jobs. I get it. Getting the job is great. Getting the job means nothing if you don't make money on it.

01

Send me two pages.

The page from your workers' comp policy showing your classifications, your rates, and your scheduled credits (hopefully you have them). And the general liability page showing the rates that apply to payroll, sales, and cost of subcontractors.

02

Give me about 10 minutes.

I run the numbers for the job you're bidding: the payroll going on it, the subs you'll use, and whether those subs are covered.

03

I call you back with the number.

The insurance cost to build into your bid. Before you bid it. Not after you finish the job. Not when the audit comes. And not when you're sitting there wondering where the heck all your profit went.

WHAT TO SEND ME

Workers' comp page:

  • Your classifications
  • Your rates
  • Your scheduled credits

General liability page:

  • Rate on payroll
  • Rate on sales
  • Rate on cost of subcontractors

Plus the job: your labor estimate and what you're paying subs.

You don't have to be a mathematician. You don't have to be an insurance expert. And you definitely don't have to be a rocket scientist. I'm not a rocket scientist either. I'm Andy the Insurance Guy.

The Money You Thought You Made...May Not End Up Being What You Actually Made!

QUICK ONE

BE HONEST. LAST JOB YOU BID...

Did you add workers' comp and general liability to the price?

THE GUY IN THE HARD HAT

I'M ANDY THE INSURANCE GUY.

I'm Andrew Ritterman. I help contractors with workers comp, general liability, business auto, and bonds. Audits, certificates, subs, additional insured wording, claims, payroll changes, vehicles, and contract requirements are all part of my work.

Got a question? Need clarification? Give me a call. I'm always available.

Andy at his desk with a policy folder and coffee

QUICK FACTS

  • Rocket scientist: No
  • Contractor insurance: Yes
  • Licensed
  • Picks up his own cell: Yes
  • Sends COIs immediately: Yes

ANDY'S DIRECT LINE

Call or text: 201-254-4117

Email: andrewritterman@gmail.com

www.AndyTheInsuranceGuy.com

Serving contractors.

STRAIGHT ANSWERS

QUESTIONS CONTRACTORS ASK ME

Andy shrugging

Why did I get a bill after my workers' comp audit?

Your policy was priced on an estimate of your payroll. After the policy year ends, the carrier's auditor counts your actual payroll by class code, adds any subcontractor you couldn't produce a certificate of insurance for, and bills the difference. More payroll than estimated, work rated in a higher class, or uninsured subs each raise the bill.

CALL ANDY THE INSURANCE GUY

SEND ME YOUR POLICIES.

Call, text photos of your policy pages, or use the form. I'll call you back.

Andy pointing at you